

Updated: October 2026
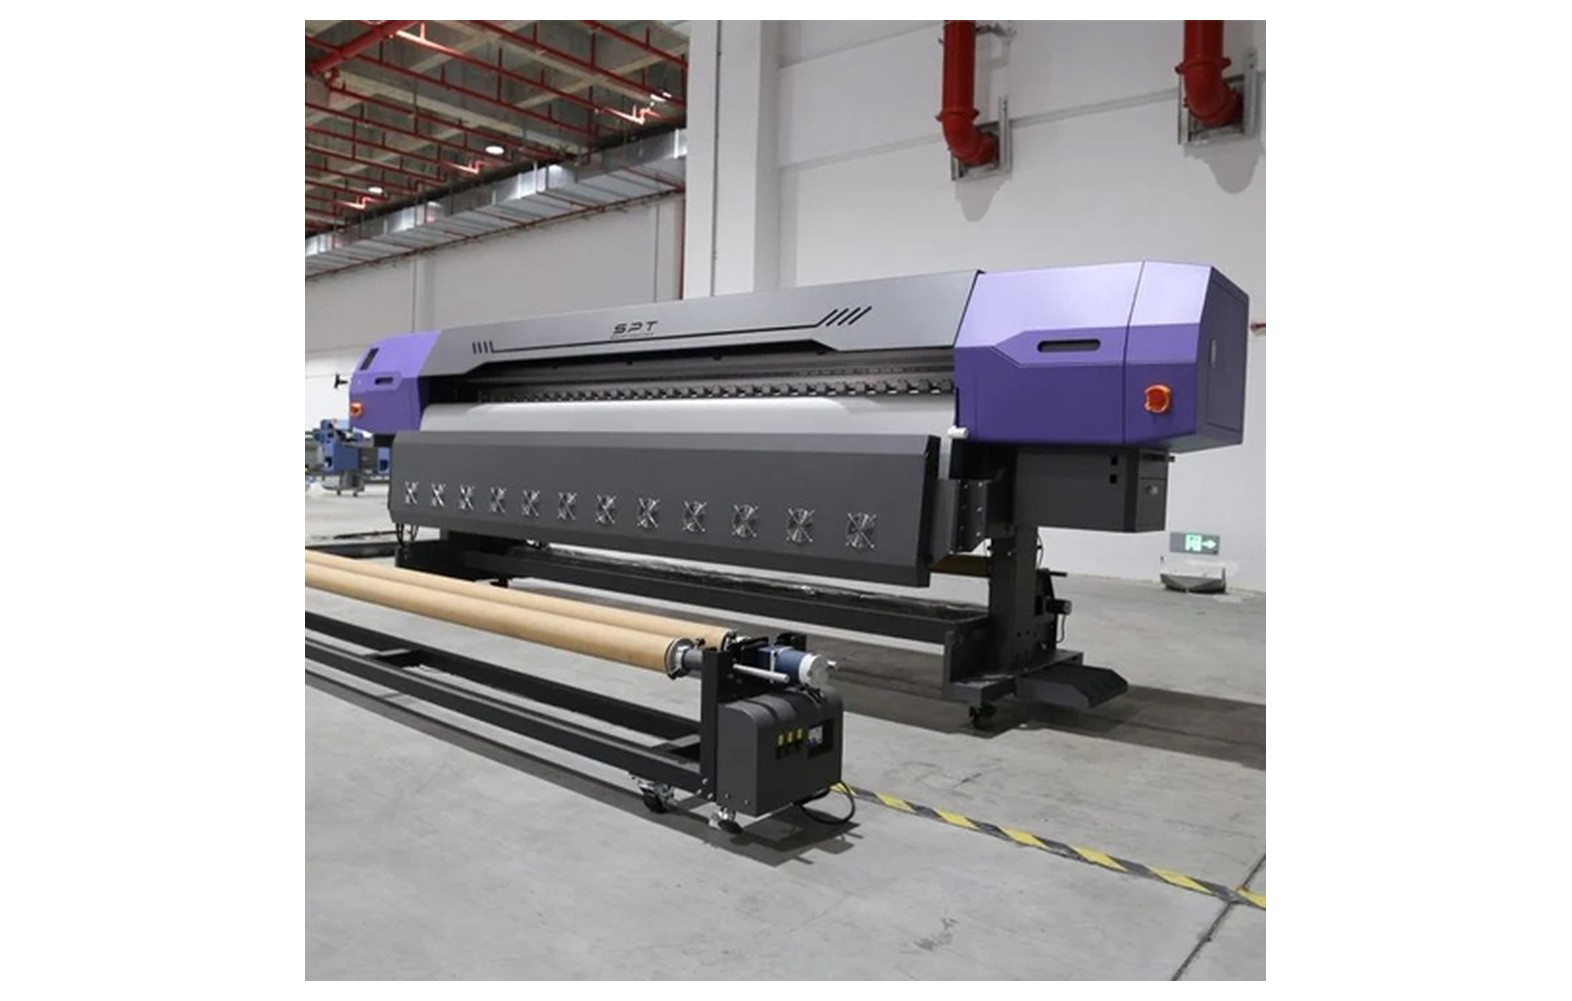
Seven out of ten flex machines in India roll into shops against borrowed money – and the difference between a smart machine loan and a bad one is often Rs 1-3 lakh in hidden cost over the tenure. Sellers advertise easy EMI loudly and the paperwork quietly. This guide opens the full finance math: down payment, monthly installment by budget, the loan routes ranked, real interest cost and the documents that get applications approved. All figures are estimates (est.).
EMI Math by Machine Budget (est.)
| Machine price | Down payment 20-30% | EMI, 36 months | EMI, 48 months | Total interest, 36 mo (est.) |
|---|---|---|---|---|
| Rs 2.5 lakh (entry 3.2 m, 2-4 head) | Rs 50,000-75,000 | Rs 6,800-8,200 | Rs 5,400-6,500 | Rs 40,000-55,000 |
| Rs 4 lakh (standard 4-head 512i) | Rs 80,000-1,20,000 | Rs 10,500-13,000 | Rs 8,500-10,300 | Rs 65,000-85,000 |
| Rs 8 lakh (8-head ready / premium build) | Rs 1.6-2.4 lakh | Rs 21,000-26,000 | Rs 17,000-20,500 | Rs 1.3-1.7 lakh |
| Rs 15 lakh (8-head production class) | Rs 3-4.5 lakh | Rs 39,000-48,500 | Rs 32,000-38,500 | Rs 2.4-3.2 lakh |
Working: 12-14% reducing balance, the range Indian equipment NBFCs quote for 1-3 year old businesses in 2026 (est.). A reliable 4-head machine therefore costs roughly what one part-time helper costs per month – see what that machine earns in the monthly income math.
The 4 Loan Routes, Ranked by Real Cost
| Route | Effective rate (est.) | Speed | Best for |
|---|---|---|---|
| Bank machinery loan incl. PM MUDRA (up to Rs 10 lakh) | 9-12% | 2-6 weeks, paperwork heavy | UDYAM-registered units with bank statements and a project report |
| NBFC equipment finance | 12-16% | 3-10 days | New businesses without long ITR history – most machines run on this |
| Dealer-arranged finance | 11-15% | Fastest, bundled with quote | Convenience – but compare against one outside NBFC quote before signing |
| CGTMSE-style collateral-free MSME loan via bank | 10-13% | 4-8 weeks | Registered MSMEs wanting no collateral on bigger machines |
Rule of thumb: bank money is cheapest but slowest; NBFC money is fastest but read the foreclosure clause. Dealer finance sits in the middle and is fine when the dealer is a verified supplier – our supplier verification guide explains how to check that first.
Paperwork That Gets Machines Approved
| Document | Why the lender wants it |
|---|---|
| UDYAM registration (free, 10 minutes online) | Unlocks MUDRA and MSME loan products |
| 6-12 months bank statement | Proves cash flow can feed the EMI |
| Machine proforma invoice on seller letterhead | The loan is disbursed against this exact paper |
| KYC plus shop electricity bill or rent agreement | Confirms the physical unit exists |
| ITR 1-2 years if available (not mandatory at NBFCs) | Drops the rate by 1-2% when present |
| Simple project report for MUDRA route | 1-2 pages: machine cost, expected print volumes, rate card, buyer list |
The Real Cost of an EMI – Read Before Signing
- Processing fee: 1-2% of the loan plus GST, paid upfront – Rs 8,400-9,500 on a Rs 4 lakh loan that brochures never mention (est.).
- Insurance: machine insurance is usually bundled or demanded separately at Rs 6,000-12,000 per year (est.).
- Advance EMI or security deposit: many NBFCs collect the first installment at disbursement – your day-one outflow is down payment plus first EMI plus fees.
- Flat rate trap: 9% flat equals roughly 16.5% reducing balance – always ask for the reducing-balance figure and compare only that.
- Foreclosure charge: 4-5% of outstanding principal; matters when a good season lets you close the loan early.
- Overdue penalty: 2-3% per month on missed EMIs plus a credit-score dent that makes the next machine costlier.
Three Rules Before You Take Machine Debt
- EMI under 30-35% of realistic billing. Not hoped billing – the billing of month one. The demand-building reality is mapped in how to start a flex printing business and rate reality in the flex printing rates per sq ft.
- Keep a 3-EMI buffer in cash. Seasonal dips and election gaps are certain; the buffer is what survives them.
- Finance the machine, never the working capital. Ink, media stock and agency credit cycles belong to your pocket – borrowing for consumables is where print shops slide under water.
Budget tight? The machines under Rs 5 lakh guide and cheapest flex machine guide show where corners can safely be cut and where they cannot, and the 4-head machine price guide benchmarks the configuration most loans are taken against.
Our Verdict
Take the EMI when the production math already works on paper: machine size fixed from real volumes (4-head vs 8-head comparison), supplier verified on spares and service (supplier verification guide), insurance and buffer in place – then the installment is a planned cost, not a gamble. UED issues NBFC-ready proforma invoices with full machine specs, assists with documentation, and pairs every financed machine with installation and operator training so billing starts on schedule. Browse the flex printing machine range, see the Gethray C-series flex machine, and check the monthly income math before you size your loan – then share your budget on the contact page for an exact quote.
FAQs – Flex Printing Machine on EMI in India 2026
Can I buy a flex printing machine on EMI in India?
Yes – through bank machinery loans (including PM MUDRA up to Rs 10 lakh), NBFC equipment finance, or dealer-arranged finance. Expect 20-30% down payment and 36-48 month tenures at 12-16% for NBFCs and 9-12% for banks (est.). Most Indian 4-head machines run on NBFC finance because it approves in 3-10 days.
What is the monthly EMI for a Rs 4 lakh flex printing machine?
With 20-30% down (Rs 80,000-1.2 lakh), the EMI runs roughly Rs 8,500-13,000 per month over 36-48 months at 10-14% (est.). Total interest over 36 months is about Rs 65,000-85,000. Always compare the reducing-balance rate, not the advertised flat rate.
Can I get a machine loan without ITR or for a new business?
Yes, via NBFC equipment finance: they accept 6-12 months of bank statements, UDYAM registration, KYC and the machine proforma invoice, at 1-3% higher rates than ITR-backed loans (est.). A co-applicant with income history and UDYAM registration both improve approval odds.
Is a MUDRA loan available for a printing machine?
Yes – PM MUDRA covers micro-enterprise machinery up to Rs 10 lakh through banks at roughly 9-12% (est.). You need UDYAM registration, a short project report (machine cost, expected volumes, rate card, buyer list) and basic KYC. It is the cheapest legitimate route but takes 2-6 weeks.
Is zero-percent EMI on printing machines real?
Rarely – the interest is usually loaded into the machine price or the tenure is very short. Compare total outflow (price plus all installments plus fees) against a cash-purchase quote rather than the EMI headline. If total outflow exceeds the cash quote by more than 12-15%, the zero-percent tag is marketing.
More flex machine buying guides: solvent machine price guide, 4-head price guide, 8-head price guide, repair and service guide, monthly income math, brand comparison guide, best flex printing machine picks for small business, flex machine price guide.
Share your hoarding sizes and target buyers on the contact page – we reply with an exact machine quote, freight and installation plan for your city, with on-site training across India.
